Although transactional activity stalled everywhere in Europe following the coronavirus outbreak, cross-border investment in particular has suffered the most, according to Larry Young, head of international investment group at BNP Paribas Real Estate.
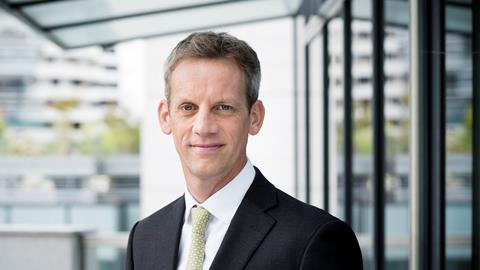
‘When the Covid-19 pandemic hit Europe earlier in the year, all investment markets were affected, no matter the reaction of each country. Cross-border investment, notably from outside Europe, has been the most impacted,’ Young told PropertyEU.
With the very cautious and slow opening of borders, and some countries suffering second waves of the crisis, Young believes that it will take time for investment markets to reach pre-crisis levels.
Before this unparalleled event, cross border investment in real estate had experienced a period of impressive performance. In 2019, foreign capital represented half of commercial real estate investment in Europe and in Q1 of 2020 reached a record level of €39 bn, a 71% year on year increase.
Certain assets have been affected by the pandemic more than others. Residential, healthcare, logistics and anything linked to groceries have understandably held up well while retail, hotels and secondary office markets have suffered. Across the world, countries have undergone different experiences linked to the severity of their lockdowns and the predominance of foreign investors.
‘The next few months are crucial, and as long as we avoid a significant second wave, and global borders are opened up again, real estate will continue to be a resilient asset during this difficult period,’ Young added.
The office and retail sectors
Office occupational markets have experienced significant drops in take-up across the main markets following the outbreak. However, vacancy levels should not increase substantially due to the strong conditions of the market before the lockdown, according to Young.
‘Rental levels are not likely to fall significantly, for core markets,’ he said. ‘Changes are being experienced as a number of occupiers are reacting to a new work dynamic that favours working from home, and some may scale back their occupational needs. The question remains as to how permanent this shift will be and if spilt office locations and co-working will be part of a new office based strategy for occupiers and tenants.’
As people start to go back to work, activity in the office investment market is picking up, as visiting properties will be easier (virtual visits during lockdown were still possible) and vendors are more willing to put properties on the market.
As Europe starts to open up, more product is comong onto the market, notably in France and Germany, and the initial feedback from bidding processes has been positive, especially for core central assets.
Retail has been amongst the asset classes that has suffered the most during the pandemic, with the crisis resulting in a wider gap between prime and sub-prime assets, regardless of the segment.
Young admits that most ongoing deals are still on hold, and retail REITs have seen their share price hit hard. However, footfall has been encouraging in places where lockdown has been lifted, and there have still been some large deals which have been finalised, notably in France and in Spain, he noted.
‘Any part of the retail sector linked to food distribution and health has understandably held up well,’ he added. ‘The retail market was already changing before Covid-19, notably with because of e-commerce – the crisis will only increase the speed of this transformation.’