



With traditional M&A routes remaining largely congested, institutional investors are increasingly turning to the infrastructure secondary market to secure liquidity and rebalance portfolios.
This shift has transformed infrastructure secondaries from a niche tool into a vital deployment engine, with overall . Rather than waiting for traditional exit windows to reopen, managers are utilising the secondary space to recycle capital efficiently into resilient, cash-generating assets.
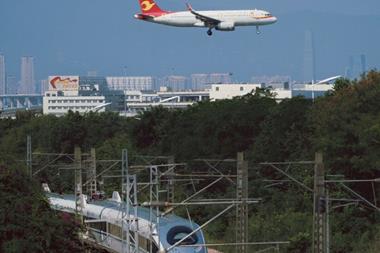
The rapid pace of capital deployment highlights the strength of the strategy. recently pushed its , anchoring its latest expansion in asset-heavy, contracted UK passenger rail and commercial aviation platforms. This market momentum is equally visible in fundraising, as seen with , which focuses 90% of its allocation on secondary transactions and has already deployed $1.2bn from the fund across 10 transactions involving 254 assets, achieving an average discount of 14% on those deals.
This preference for steady, proven assets over speculative growth is a strategy shared by these institutional managers. Notably, Pantheon, which ranked 28th in the latest , focuses on underwriting rigour over speculative market trends.
As Andrea Echberg, partner and global head of infrastructure at Pantheon, puts it: “It’s more around the detail and the discipline of the underwriting than necessarily what the big themes are. And I think that’s the challenge that we face today – sticking to that discipline when there’s a lot of exuberance about themes.�
This news briefing was published last week. If you would like to receive it regularly, on your ‘Â鶹ӳ» Real Assets profile’, go to and select any from the list.
To read the latest Â鶹ӳ» Real Assets magazine click here.